Rhenium supply depends on copper–molybdenum processing, while demand is concentrated in turbine superalloys and petroleum catalysts. Most trading takes place through specialized bilateral contracts rather than an exchange with continuous executable bids. Private resale therefore depends on matching a documented parcel to an industrial buyer or trader.
A certificate for 99.99%-pure rhenium pellets does not establish that a turbine-alloy producer will accept the parcel. Acceptance also depends on the material’s form, impurity profile, provenance and compatibility with the buyer’s process. That gap between owning high-purity metal and supplying acceptable industrial feedstock explains why private rhenium holdings lack a bullion-style resale market.
Key points
- Primary supply is a byproduct stream. Suitable molybdenite must be mined, roasted and processed through rhenium-recovery equipment; a higher rhenium price cannot independently increase host-metal production.
- Demand is concentrated in qualified industrial applications. The USGS 2025 end-use breakdown assigns an estimated 80% to superalloys and 15% to petroleum-reforming catalysts.
- Recovery does not necessarily create merchant inventory. Catalyst returns can remain within closed loops, while turbine scrap can retain its value as alloy feedstock rather than become isolated rhenium metal.
- A reference price is not a parcel-specific bid. Resale generally requires negotiation with a buyer whose acceptance criteria match the material’s form, quality and quantity.
Why a higher rhenium price cannot switch on a mine
The U.S. Geological Survey’s Mineral Commodity Summaries 2025, published on January 31, 2025, estimated world primary rhenium production in 2024 at approximately 79.8 metric tonnes of contained rhenium. U.S. primary production was approximately 9,500 kilograms, compared with 9,410 kilograms in 2023, from molybdenum-concentrate roasting in Arizona and Montana.
The production route matters more than the small tonnage alone. Primary rhenium is recovered mainly from molybdenite concentrates associated with porphyry copper–molybdenum deposits, rather than from dedicated rhenium mines. During roasting, rhenium volatilizes and is captured from roaster gases and flue dust. Chemical processing then produces ammonium perrhenate (APR), perrhenic acid or rhenium metal.
Recoverable supply therefore depends on several linked conditions: copper and molybdenum mining, the rhenium content of the concentrate, roasting throughput and suitable capture and refining infrastructure. Copper production alone does not establish rhenium production. The associated molybdenum concentrate must reach a processing route equipped to recover the rhenium.
A stronger rhenium price can improve the incentive to recover metal from an existing stream, but it cannot independently determine host-metal mining volumes or create suitable concentrate. A production assessment consequently needs evidence about the deposit, concentrate route and recovery plant—not merely a copper mine’s output or a stated rhenium resource.
Superalloy demand is tied to qualified components
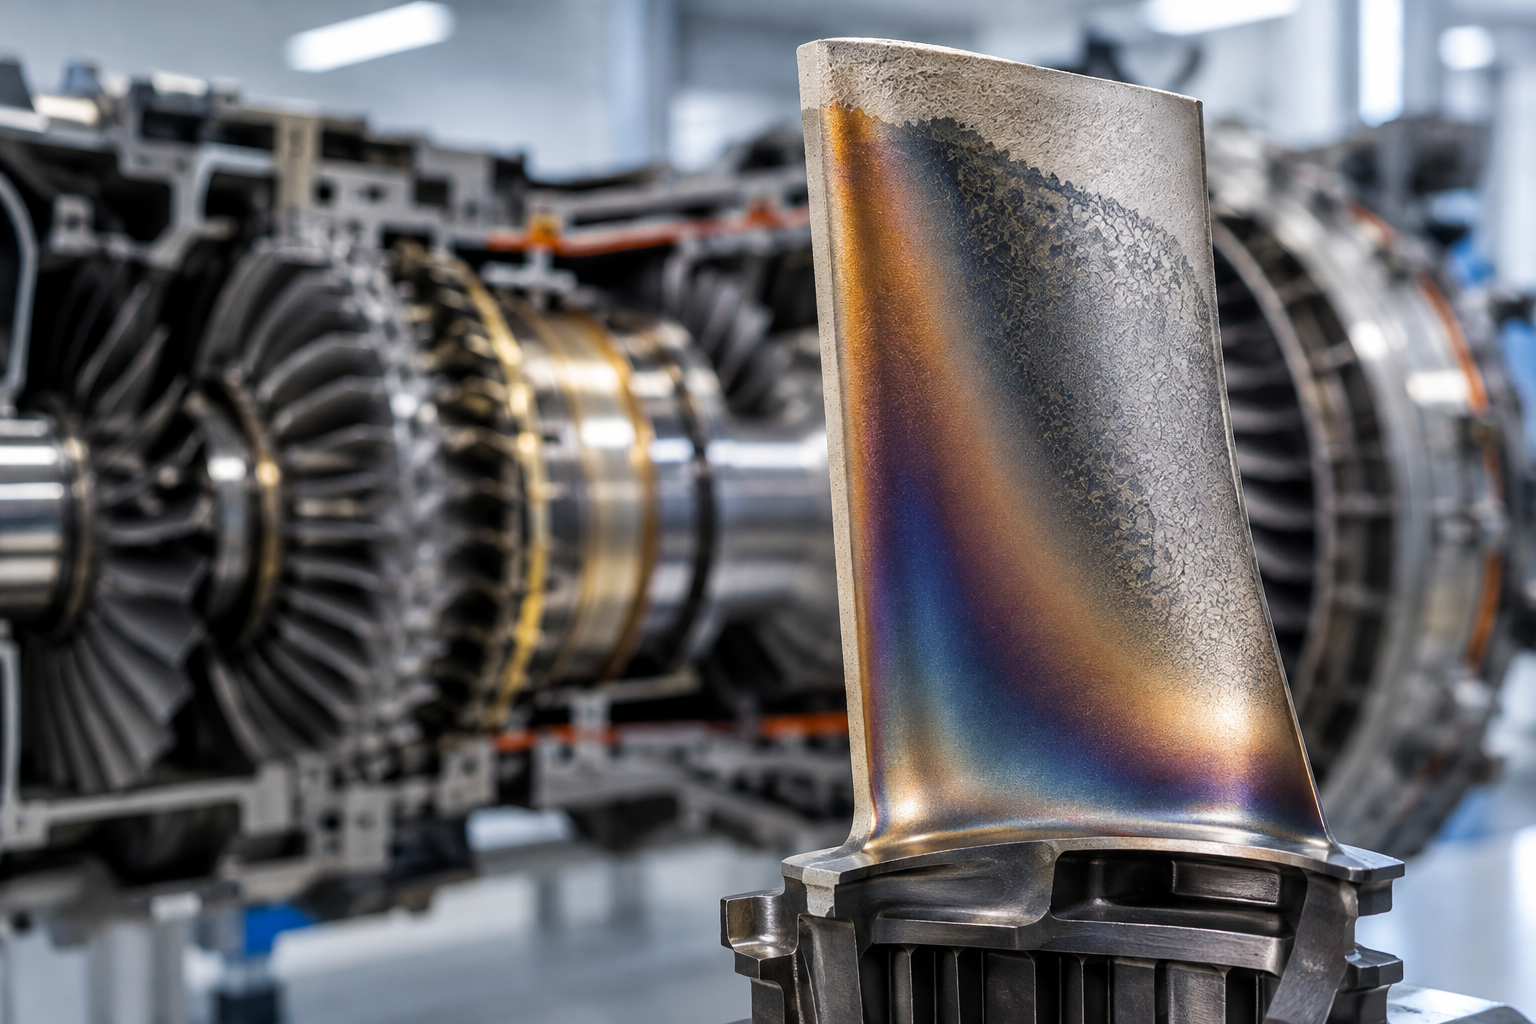
Rhenium’s dominant application is an alloying addition to nickel-base single-crystal and directionally solidified superalloys used in turbine blades and vanes. It improves high-temperature strength and creep resistance—the component’s resistance to deformation under sustained load at elevated temperature.
The USGS 2025 summary assigns an estimated 80% of rhenium end use to superalloys, 15% to petroleum-reforming catalysts and the remaining 5% to smaller applications, including other high-temperature alloys, thermocouples and electrical contacts. Aircraft-engine and industrial-turbine production therefore matter directly to rhenium demand.
A turbine blade’s alloy belongs to a qualified engine or turbine system. A change in rhenium price does not make another composition immediately interchangeable. Thrifting—reducing the amount used—along with alloy redesign and substitution can lower consumption, but those responses depend on qualification cycles and process economics. Qualification constrains substitution without guaranteeing an unchanged consumption rate.
These requirements also shape resale. Industrial need for rhenium does not mean that an engine-material supplier will purchase an unfamiliar private parcel. The relevant question is whether that parcel satisfies the purchaser’s feedstock requirements, including composition, form, traceability and quantity.
Recycling does not necessarily release metal onto the market
Secondary supply follows different routes. USGS describes hydrometallurgical recovery—chemical separation using aqueous solutions—from nickel-base superalloy scrap, including turbine blades and vanes, and recovery from spent petroleum catalysts. Its 2026 summary cites industry estimates of 20,000–25,000 kilograms of secondary rhenium production in 2025, excluding catalyst rhenium retained in closed-loop systems.
In catalyst recovery, the recovered rhenium can return to the oil company or catalyst producer for new catalyst manufacture without becoming freely available merchant inventory. Turbine scrap can also become engine revert: superalloy meltstock that preserves alloy value without separating all its rhenium into elemental metal.
Neither “recycled” nor “recoverable” is therefore a sufficient description of available supply. For aerospace scrap, assessment of direct reuse or chemical recovery turns on the alloy composition, coatings, contamination, traceability and any ownership restrictions. A private holder of alloy scrap owns a different product from a holder of refined pellets, even if both parcels have documented rhenium content.
What the published prices actually describe
USGS publishes annual average prices for 99.99%-pure rhenium metal pellets and catalytic-grade APR, using Argus Non-Ferrous Markets as its price source. These are references for specified industrial products, not continuously executable retail quotations.
| Price observation year | Metal pellets, 99.99% pure (US$/kg) | Catalytic-grade APR (US$/kg) | USGS publication |
|---|---|---|---|
| 2023 annual average | 1,070 | 920 | Mineral Commodity Summaries 2025 |
| 2024 annual average | 1,370 | 1,270 | Mineral Commodity Summaries 2025 |
| 2025 estimated annual average | 2,600 | 2,300 | Mineral Commodity Summaries 2026 |
The US$2,600/kg pellet figure is an estimate for 2025 published in the 2026 summary. It is not a current purchase offer for an individually held kilogram. A parcel-level valuation must separately account for applicable assay, handling, custody, shipping, insurance, dealer charges and taxes rather than treating the annual average as net sale proceeds.
The principal rhenium price drivers combine industrial demand with constrained feedstock: aircraft-engine and turbine production, refinery catalyst requirements, copper–molybdenum concentrate output, recovery rates, aerospace scrap availability and inventory decisions. Recycling adds another constraint. Industry sources cited in the USGS 2026 summary indicated that some superalloy-scrap recovery routes needed sustained prices above US$3,000/kg to offset processing costs. That is a route-specific processing hurdle, not a universal production cost or guaranteed price floor.
The product form determines the potential buyer
A statement that a parcel contains “rhenium” leaves the commercial product undefined. The following forms raise different acceptance questions and cannot be treated as interchangeable holdings. The evidence relevant to a particular transaction depends on the purchaser’s specification.
| Form | Evidence to assess against the buyer’s requirements | Private-resale failure mode |
|---|---|---|
| Metal pellets | Lot-linked assay, impurity results, net mass, packaging and acceptance of the pellet specification. | A high-purity certificate is treated as sufficient evidence of aerospace-feedstock eligibility. |
| Ammonium perrhenate | Chemical identity, rhenium content, grade, impurity profile and the buyer’s pricing basis. | An APR parcel is valued against a metal-pellet quotation without accounting for product differences or conversion requirements. |
| Metal powder | Purity, any required particle-size specification, contamination controls and package condition. | Chemical purity is documented, but particle characteristics or packaging do not meet the purchaser’s process requirements. |
| Rhenium-bearing alloy scrap or revert | Alloy composition, rhenium content, coatings, traceability, ownership and acceptance by a recycler or meltstock buyer. | Contained rhenium is valued as refined metal without allowing for recovery costs or feedstock restrictions. |
For APR, a quotation needs an explicit denominator: mass of product or contained rhenium. For a proposed conversion between APR, powder, pellets or scrap, the commercial assessment needs to address processing charges, material losses, post-conversion assay requirements and responsibility for qualification. A buyer for one form is not evidence of an exit for another.
What makes a private parcel assessable
An assay linked to the actual material
The analytical file should connect the producer or refiner certificate to the lot number, net mass and package identifiers. Where independent testing is commissioned or required by the buyer, the laboratory report’s method, date, reporting limits and sample-to-lot relationship determine what the result supports. A certificate for an unidentified sample does not establish the composition of an entire holding.
The purity statement’s reporting basis and impurity results matter alongside the headline percentage. The relevant impurity limits come from the purchaser’s specification rather than a universal acceptance standard for private rhenium holdings. Appearance alone does not document the lot’s chemical form, purity or provenance.
Title and custody records that preserve lot identity
Provenance review connects the parcel to its producer, refiner or recycler and subsequent transfers. For recovered aerospace material, ownership of the feedstock and rights to the recovered material are also relevant. A description such as “recycled rhenium” does not identify the recovery plant or establish title.
A specialist custodian or resale counterparty may require records covering warehouse jurisdiction, segregated or pooled status, package identifiers, seals, intake weights and release controls. Package condition and contamination controls may also affect acceptance of powder or pellets. The purpose is to connect the documented material to the parcel held in storage; these records are not a universal statutory checklist.
Insurance requires a separate review of the policy or coverage schedule for the actual rhenium form, insured interest, valuation basis and covered losses. Neither a custody receipt nor a published pellet price establishes those terms. Storage and insurance charges belong in the parcel’s cost assessment under the relevant agreements.
A buyer and terms for this form and quantity
The most direct evidence of resale liquidity is a purchasing entity willing to quote for the documented parcel. Assessment of that quote turns on accepted form and purity, quantity, assay tolerances, delivery conditions, settlement currency, fees and any conversion deductions. An indicative reference or a buyback statement subject to later material acceptance leaves the exit conditional.
This is where small-lot economics become visible. At the 2024 published pellet average, one kilogram represented US$1,370 before parcel-specific transaction and holding costs. Assay, secure handling and shipment therefore need to be assessed against the parcel’s value rather than assumed negligible. The annual reference price cannot establish a small-lot dealing spread.
A transaction-specific jurisdictional assessment
Refined pellets, powders, spent catalysts and aerospace scrap are different starting points for customs, transport and export-control analysis. That assessment depends on the material, origin, seller, carrier, consignee, destination and intended end use. Calling a parcel “investment rhenium” does not settle its classification or the requirements applicable to its movement.
Conclusion: scarcity is not an exit mechanism
Rhenium’s small primary output and demanding turbine applications explain a specialized, contract-led market rather than a ready resale channel for private parcels. Lot-linked composition evidence, title and custody records make a holding assessable; a buyer’s acceptance criteria and commercial terms determine whether it can enter an industrial supply chain. Scarcity can influence price, but it cannot substitute for that connection.
Sources
- USGS, Mineral Commodity Summaries 2025: Rhenium — 2024 production, end uses, recovery routes and historical industrial prices.
- USGS, Mineral Commodity Summaries 2025 — publication dated January 31, 2025.
- USGS, Mineral Commodity Summaries 2026: Rhenium — 2025 price estimates, secondary-production estimates and recycling economics.